M&A in testing, inspection, certification and compliance sector remains upbeat

There is a strong wave of merger and acquisition (M&A) activity sweeping through the global testing, inspection, certification, and compliance (TICC) sector despite global economic and political uncertainty. That is according to a report from corporate finance advisory firm Oaklins.
Even as macroeconomic and geopolitical risk is on the rise – with conflict in the Middle East, inflation and lingering stagnation – corporate dealmaking in the TICC industry has maintained strong momentum over the past year. Valuation levels of listed companies in the sector have remained stable, if not slightly trending upward in recent years.
According to the findings, the direct impact of recent political tensions, including developments in the Middle East, has remained relatively limited for these businesses. In fact, total transaction numbers over the past 12 months exceeded the average levels observed since 2023.
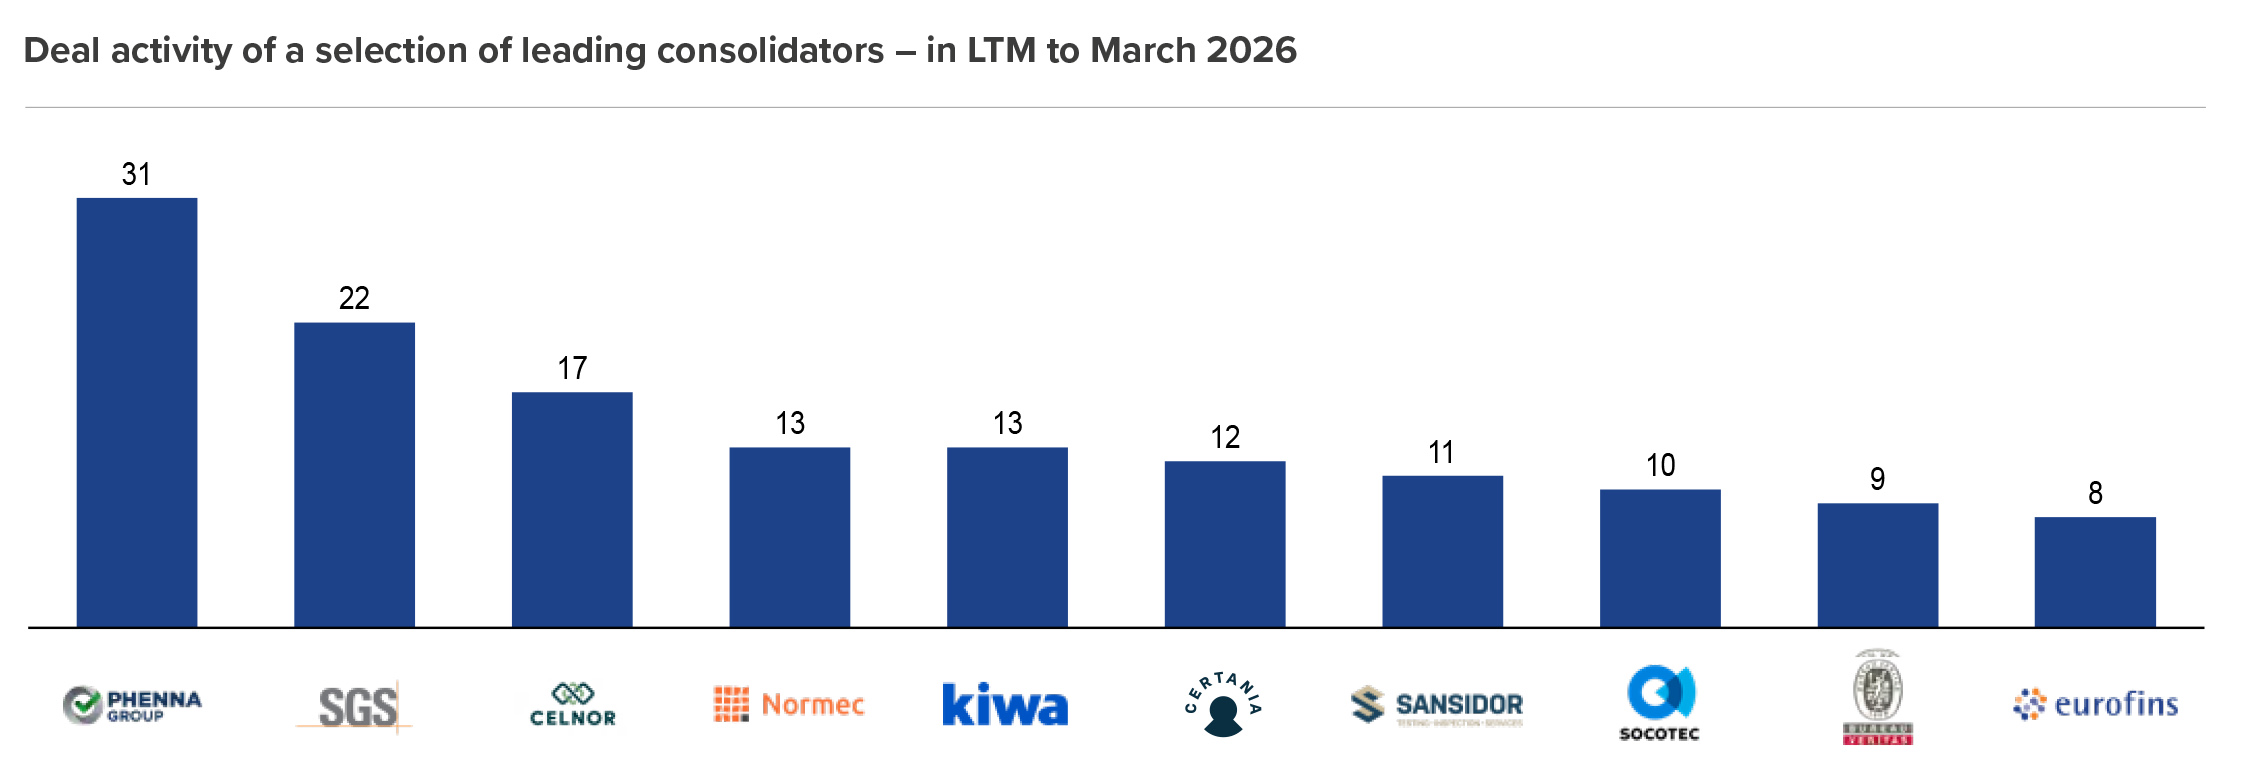
This sustained momentum is largely driven by a small group of highly active, well-funded corporate buyers that the report refers to as ‘consolidators’. The top 10 buyers accounted for 43% of all transactions during this period, while the top 15 buyers were responsible for 51% of the total market deals.
“Over the past decade, we have seen significant activity from large consolidators, primarily in Continental Europe and the United Kingdom, as well as within established verticals,” said Tijn Bastiaans, head of business support services and private equity at Oaklins in the Netherlands.
Buyers look to new markets
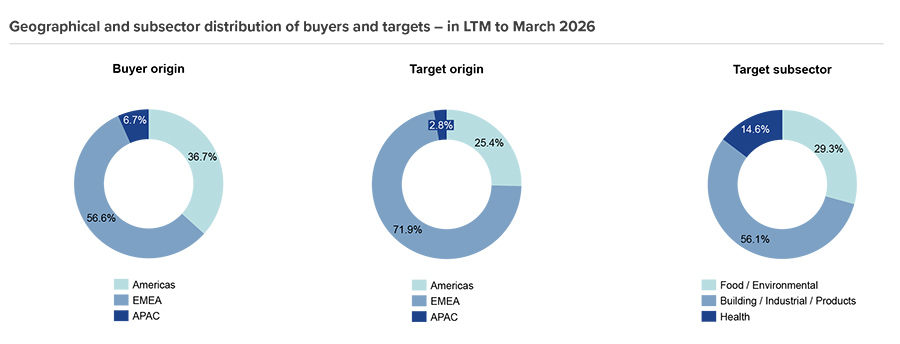
According to the authors, a significant shift is occurring as these major industry buyers increasingly expand outside of their traditional territories. For the past decade, corporate buyers focused heavily on consolidation within Continental Europe and the United Kingdom. While these original markets still offer ample opportunities for organic growth, buyers are now aggressively crossing the Atlantic to enter the United States.
This geographic trend materialized heavily when Netherlands-based Normec Group completed its first acquisitions in the United States in August 2025. Other major European players, including Phenna Group and Celnor, also entered the US market through their initial transactions in the same year.
This expansion strategy allows large firms to maintain their rapid acquisition pace by tapping into a large American market that has a growing demand for high-quality safety and compliance services.
Companies venture into adjacent fields
Corporate buyers are also unlocking new growth by purchasing businesses in entirely adjacent fields. According to the report, firms are no longer sticking strictly to their legacy niches.
For example, the Netherlands-based firm Sansidor expanded into the maintenance, inspection, and management of elevators, escalators, automatic doors, and facade installations through its acquisition of a company called DLR Eurlicon. This new direction builds upon the previous expansion of Sansidor into environmental, soil, and geotechnical services.
The report further highlighted the massive acquisition scale achieved by specific market players. Phenna Group led the industry by completing 31 acquisitions over the 12-month period, focused mainly on the building, industrial, and products sectors. Meanwhile, Switzerland-based SGS completed 22 acquisitions, while Celnor closed 17 deals.
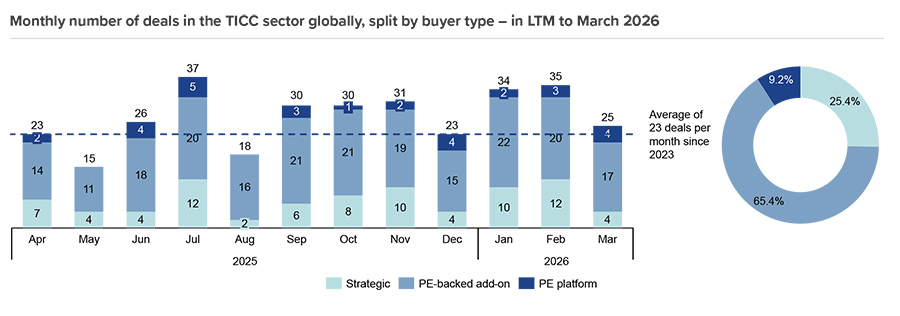
Overall, the sector has seen an average of 23 deals per month since 2023, with an uptick in the first two months of this year. The majority (over 65%) of those deals were private equity-backed add-ons, though a significant portion were strategic M&As.
Future growth powered by tech
According to corporate leaders in the sector, the overarching goal of this aggressive expansion is to build the necessary scale to invest in modern organizational capabilities. In an interview as part of the Oaklin’s study, Luc Leroy, CEO of global compliance player Kiwa, noted that the ideal size for a firm in this industry is between €2.5 billion and €4 billion in revenue.
“At that scale, we can effectively follow our clients globally while also generating the returns needed to invest in critical capabilities such as IT, data and AI,” said Leroy. “Growth is therefore not an end in itself, but a means to strengthen our service offering and future-proof the organization.”
Because only a few large players in the safety and compliance sector currently excel in data and software automation, bringing in new technologies is a major competitive opportunity to future-proof operations.
“While the market trend continues to evolve, with ample opportunities for further organic and inorganic growth, consolidators are increasingly expanding into new verticals and geographies, such as the US, to accelerate growth and to maintain their acquisition pace,” said Bastiaans.