Study: AI is reshaping automotive finance despite scaling challenges

New digital-native companies and financial technology players are aggressively capturing market share in the automotive financing sector, setting up a massive industry consolidation that could displace conventional lenders within just the next few years.
These agile software-driven firms are projected to dramatically expand their influence, moving from managing just 14% of financing decisions today to approximately 70% in the near future, according to a new joint industry study conducted by Eurogroup Consulting and the ESCP Business School.
The rapid shift underscores a broader transformation across the automotive lending landscape, where automated algorithms are quickly becoming the norm. The study’s findings highlight how incumbent operators are finding it exceptionally difficult to replicate this level of success.
Less than a quarter of traditional banks have managed to move their AI initiatives successfully from the initial pilot stage to full-scale corporate implementation. Instead, the vast majority of established institutions remain trapped in limited, localized pilot programs. This execution bottleneck means that while the broader financial industry has high expectations for technological progress, traditional auto finance firms are struggling to translate corporate ambition into practical reality.
Trouble with governance and integration
The primary reason behind this bottleneck is an internal failure to build mature corporate structures capable of handling advanced automation. Research data shows that 71% of organizations currently operate with less than mature AI governance models.
Without structured management oversight and centralized policies, tech initiatives end up scattered across different departments of a business. This fragmentation makes it much harder for institutions to unify data metrics, making it virtually impossible to establish a single source of truth across various operational units.
Compounding this problem is a profound lack of regulatory preparedness. The study reveals that only 11% of financial services firms are fully prepared to comply with hugely consequential regulatory frameworks that are set to come into play soon, like the European Union AI Act.
Because advanced software systems cannot guarantee flawless execution, financial institutions are still deeply anxious about errors. For example, a minor 1% error in credit risk scoring can instantly cause millions of euros in financial losses for a major lending business.
In order to mitigate this vulnerability, risk managers continue to rely heavily on manual human oversight, which inadvertently slows down customer onboarding and counteracts the efficiency gains promised by modern digital systems.
Operational focus over strategic innovation
Today, successful deployment of AI by traditional automotive lenders is almost exclusively confined to customer support and minor back-office efficiency tasks rather than core strategic decision-making.
Interviews with market operators confirm that software is often used to fix fragmented customer-facing support in routing phone calls, converting speech to text, and operating basic chatbots. Software applications are also frequently used to automate routine administrative tasks, handle internal data documentation, and send automated payment reminders to borrowers.
However, when it comes to the critical phases of the automotive customer journey – such as personalizing financing options or evaluating creditworthiness – the sector falls short. Around 30% to 35% of lending applications are fully automated, leaving the remaining vast majority reliant on manual review. Most digital finance simulations still depend entirely on static rules, which prevents organizations from tailoring dynamic lease or loan packages to individual consumer budget profiles.
Building a roadmap to transformation
To address this massive technological gap, the study urges automotive financial operators to put steering committees in place. These committees must bridge the gap between technical specialists and traditional management by defining a standardized regulatory framework aimed at helping new applications scale.
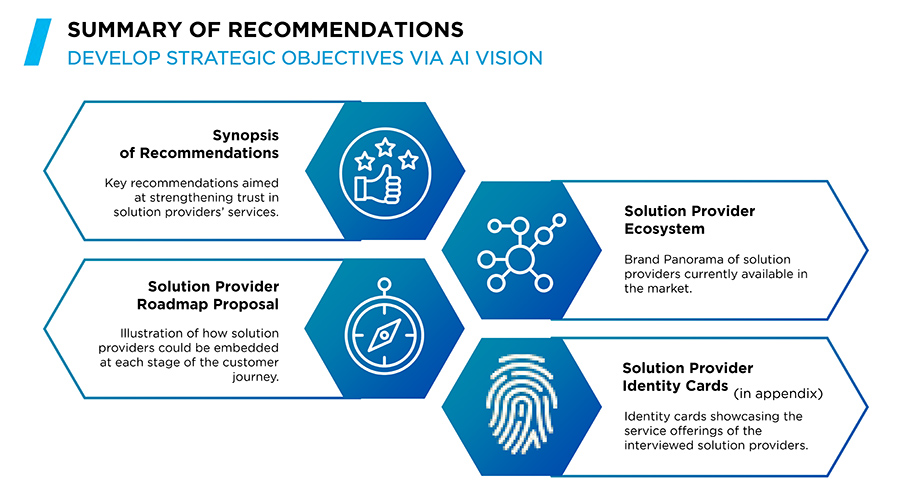
Financial operators are also encouraged to build centralized data banks with unified definitions to ensure absolute consistency and security before trying to roll out complex software models.
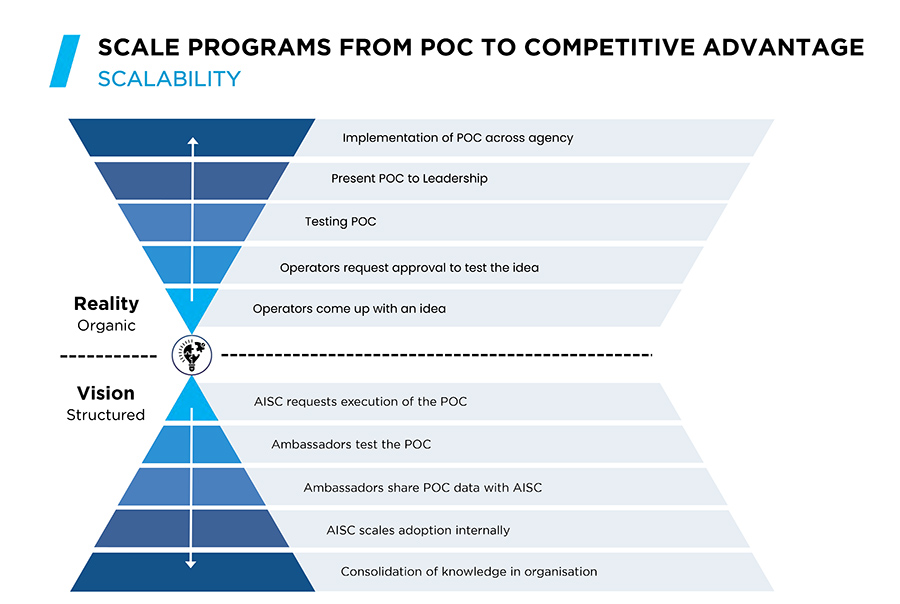
Finally, the study stresses that successful change management requires a blend of top-down corporate leadership and bottom-up engagement. Financial operators must actively train and deploy volunteer technology ambassadors across different business branches to help daily staff transition away from manual data validation.
Meanwhile, third-party solution providers must focus on delivering enterprise-grade, low-error software products that integrate smoothly into existing legacy systems without forcing disruptive organizational overhauls. If traditional auto finance players fail to implement these foundational structural changes over the next 18 months, they risk permanently losing the market to highly efficient digital native competitors.