Floriculture M&A in full bloom as deal activity rises in first half of 2026

Dealmaking activity in the floriculture sector continued its positive trajectory in the first half of 2026, with 65 transactions recorded across the value chain, according to a report from Oaklins. The activity reflects an ongoing trend of consolidation across the sector.
The sector’s H1 performance marks an increase compared to sixty-two transactions in the second half of 2025 and forty-seven transactions in the first half of 2025, confirming that the recovery observed since late 2024 has translated into sustained momentum across the industry.
Transaction activity spanned multiple regions globally, featuring numerous deals across the United States, the United Kingdom, the Netherlands, Spain, France, Sweden, Canada, and other international markets. The equipment segment currently has the highest valuation, around double some of the other segments.
A prominent pattern across these regions is a lot of both cross-border and domestic consolidation, where larger parent companies and investment firms acquire specialized nurseries, family-owned operations, and regional suppliers to build larger scale.
The current M&A environment reflects a balance between improving market conditions and ongoing structural pressures. While energy costs and inflationary pressures have moderated compared to previous years, companies continue to navigate selective cost pressures, labor constraints, financing discipline and margin pressure.
These dynamics continue to drive consolidation, particularly among founder-owned businesses, specialist growers, garden centers and technical suppliers seeking scale and operational resilience. Although short-term volatility may persist, underlying fundamentals suggest continued M&A activity for well-positioned companies across the sector, the Oaklins report notes.
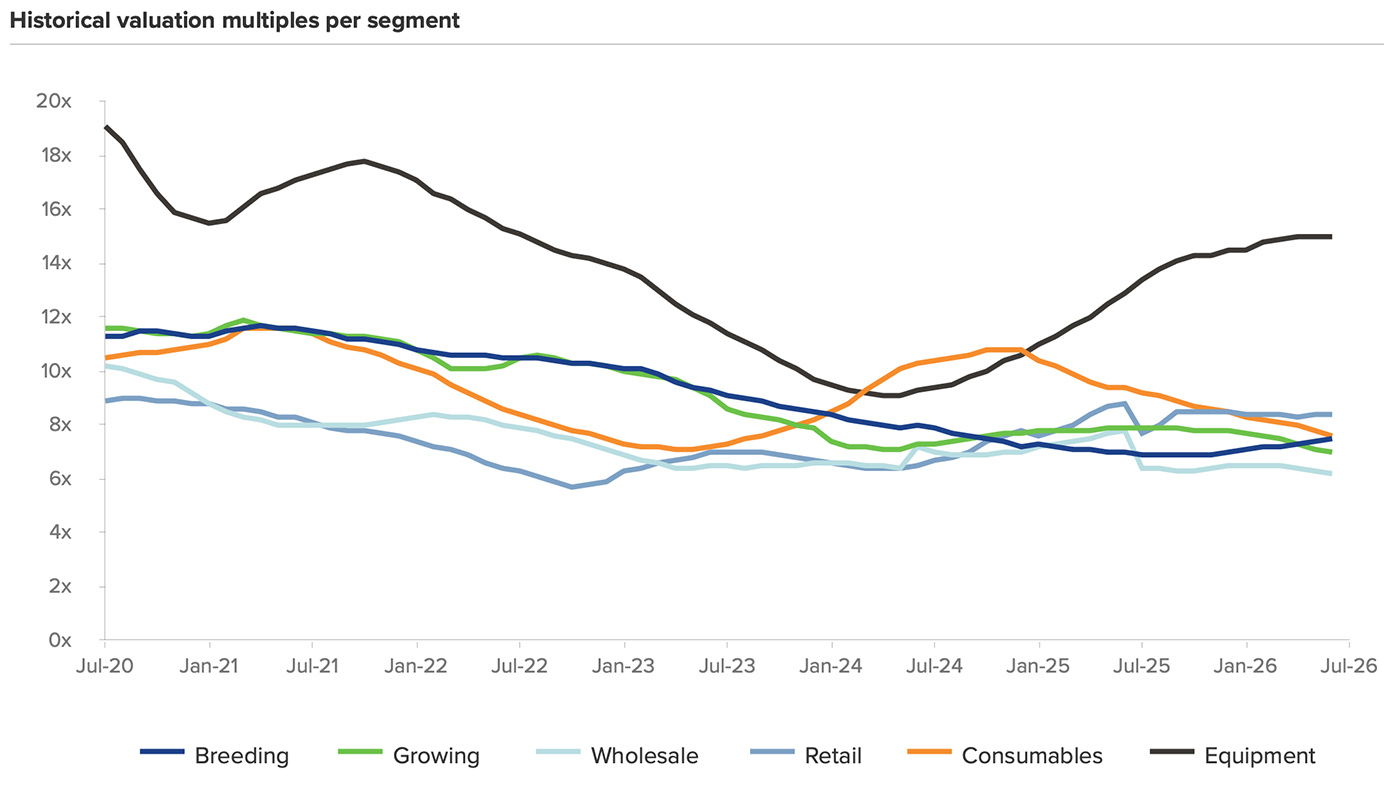
Segment performance
Retail remained the most active segment in terms of M&A during this period, recording eighteen transactions across garden centers, online plant retail, and florist networks. This segment is dominated by large commercial chains aimed at consumers.
Activity was driven by continuous consolidation among garden center groups, including multiple acquisitions by British Garden Centres and Blue Diamond Garden Centres, as well as ongoing expansion by retail florist platforms such as Family Flowers. The sustained deal flow highlights the relevance of scale, geographic density, and local brand continuity in consumer-facing markets.
Investor involvement
Financial investors also remained active across the floriculture value chain, with notable investments in retail, consumables, growing, and technical horticulture services. Investor activity was particularly visible in scalable platforms and businesses benefiting from consolidation potential. Private equity activity is again, like last year, increasingly a factor.
Notable examples include German private equity firm Paragon Partners acquiring Baldur-Garten, Nord Capital Partenaires investing in Promesse de Fleurs in the French market, and UK investment trust Caledonia Investments taking a stake in Blue Diamond Garden Centres. This activity illustrates ongoing financial sponsor interest in segments with recurring demand and strong market positions.
Future outlook and strategic drivers
Oaklins remains cautiously optimistic about floriculture market activity for the remainder of the year. Strategic buyers continue to pursue acquisitions to expand geographic coverage, strengthen supply chains, and broaden product portfolios.
Although short-term volatility may persist, underlying fundamentals suggest continued engagement for well-positioned companies across the sector as businesses seek operational resilience and scale. “As floriculture M&A activity remained strong in the first half of 2026, we continue to see consolidation as a key theme across the sector,” said Frank de Hek, partner at Oaklins.
“Strategic buyers and financial sponsors are actively pursuing opportunities to build scale, strengthen supply chains and expand into attractive growth segments, which is also reflected in the breadth and quality of our current pipeline. To a certain extent, its also a catch up of transactions that did not take place during the volatility years 2020-2024.”